




The Supreme Court of the Commonwealth of the Northern Mariana Islands recently ruled on a case involving a vehicle accident and an insurance claim. The court upheld a lower court's decision that Marianas Insurance Company (MICO) was justified in denying coverage to Ismail Hossain for damages to his car. This ruling affects Hossain and others who may find themselves in similar situations regarding insurance claims.
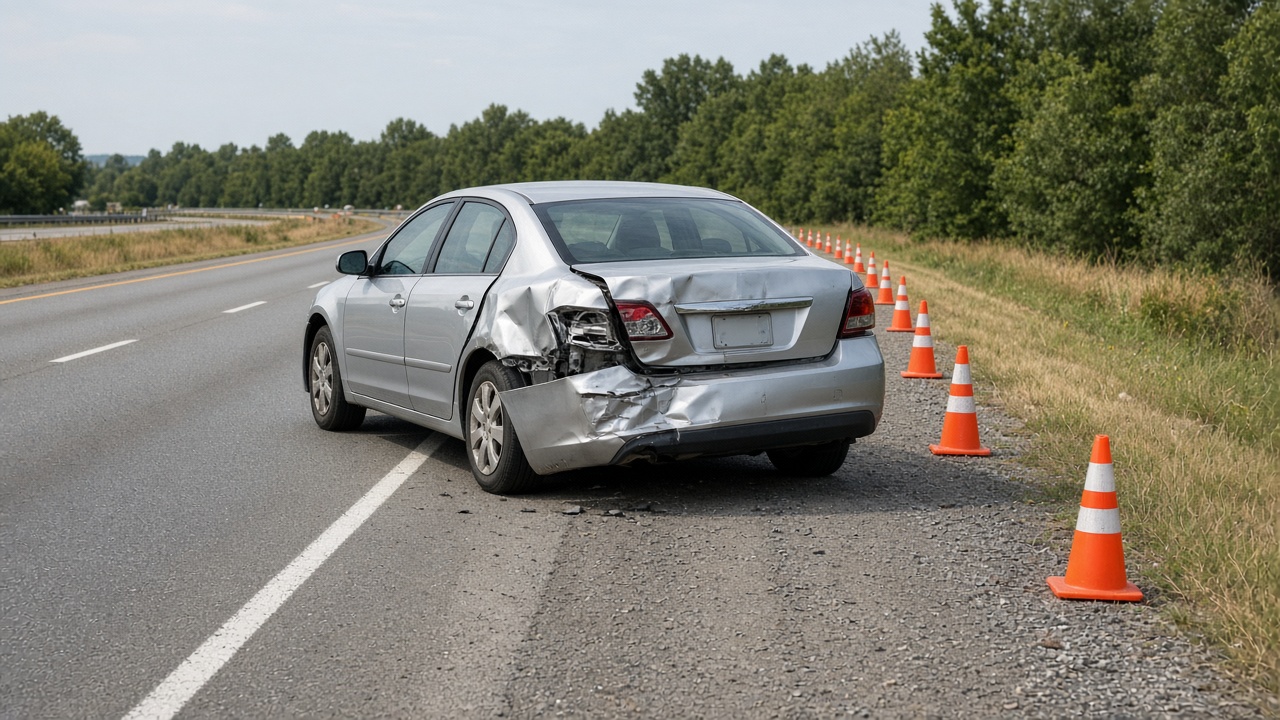
The case, Marianas Ins. Co. v. Ismail Hossain, was filed on December 18, 2017, under docket number 2016-SCC-0015-CIV. The dispute arose when Hossain's vehicle was involved in a two-car accident in August 2011. At the time of the accident, Hossain was off-island and had left his car in the care of a friend, who then allowed another individual, Cheng Hu Zheng, to drive it. After the accident, MICO denied Hossain's insurance claim, stating that the vehicle was being used as a 'public or livery conveyance,' which was excluded from coverage under the policy.
The case reached the Supreme Court after Hossain appealed the trial court's decision. He argued that the court made errors by admitting hearsay evidence from insurance adjuster reports and concluding that his vehicle was used as a public conveyance without sufficient evidence. The trial court had found in favor of MICO, leading to Hossain's appeal.
In its ruling, the Supreme Court affirmed the trial court's decision, stating that the admission of the insurance adjusters' reports was justified under the business records exception to the hearsay rule. The court explained that the reports were made in the normal course of business and were deemed trustworthy. Chief Justice Alexandro C. Castro, along with Associate Justices John A. Manglona and Perry B. Inos, agreed on this point.
The court noted, 'The adjustors’ reports were prepared in the normal course of business,' and concluded that the trial court did not abuse its discretion in admitting the evidence. The ruling emphasized that the insurance adjusters' role is to investigate claims and ascertain the facts surrounding them.
Regarding the determination that Hossain's vehicle was used as a public or livery conveyance, the court found sufficient evidence to support this conclusion. Testimony indicated that Zheng had a passenger in the vehicle at the time of the accident, and MICO adjusters observed Zheng picking up and dropping off passengers in another vehicle owned by Hossain. The court stated, 'the evidence presented [was] sufficient to show that the option for transportation in Hossain’s car was generally available to the public.'
The ruling signifies the importance of understanding the terms of insurance policies and the circumstances under which coverage may be denied. It also highlights the role of evidence in determining the outcome of insurance claims. The court's decision reinforces the need for policyholders to ensure that their vehicles are not used in ways that could void their insurance coverage.
Moving forward, this ruling may influence how insurance companies handle claims involving vehicles used for public transportation. It serves as a reminder for vehicle owners to be cautious about who they allow to drive their cars and how those vehicles are used. The decision may also affect future cases involving similar disputes over insurance coverage exclusions.
As for what’s next, Hossain may consider appealing the decision, but the court's ruling is final unless a higher court decides to take up the case. There are no related cases pending at this time. The court's decision in this matter serves as a precedent for similar disputes in the future.